Bear Run · Saraland
How Much Does It Really Cost to Buy a Home in Bear Run?
The price is one number. The payment, the cash to close and what you spend after you get the keys are the rest of it.
- Builder
- D.R. Horton
- Advertised from
- $329,900 (at writing)
- Builder's lender
- DHI Mortgage
- Compare
- Loan Estimates from DHI and an outside lender
- Construction
- FORTIFIED Gold certificate, per D.R. Horton
One of the easiest mistakes to make when you're shopping new construction is looking at the price of the house and assuming that tells you what it will cost you. It doesn't.
If you're looking at Bear Run in Saraland, the purchase price is only one part of the equation. The financing can matter just as much, and sometimes more. That's especially true with D.R. Horton, because it has an affiliated mortgage company, DHI Mortgage, and builder financing incentives can change the math dramatically.
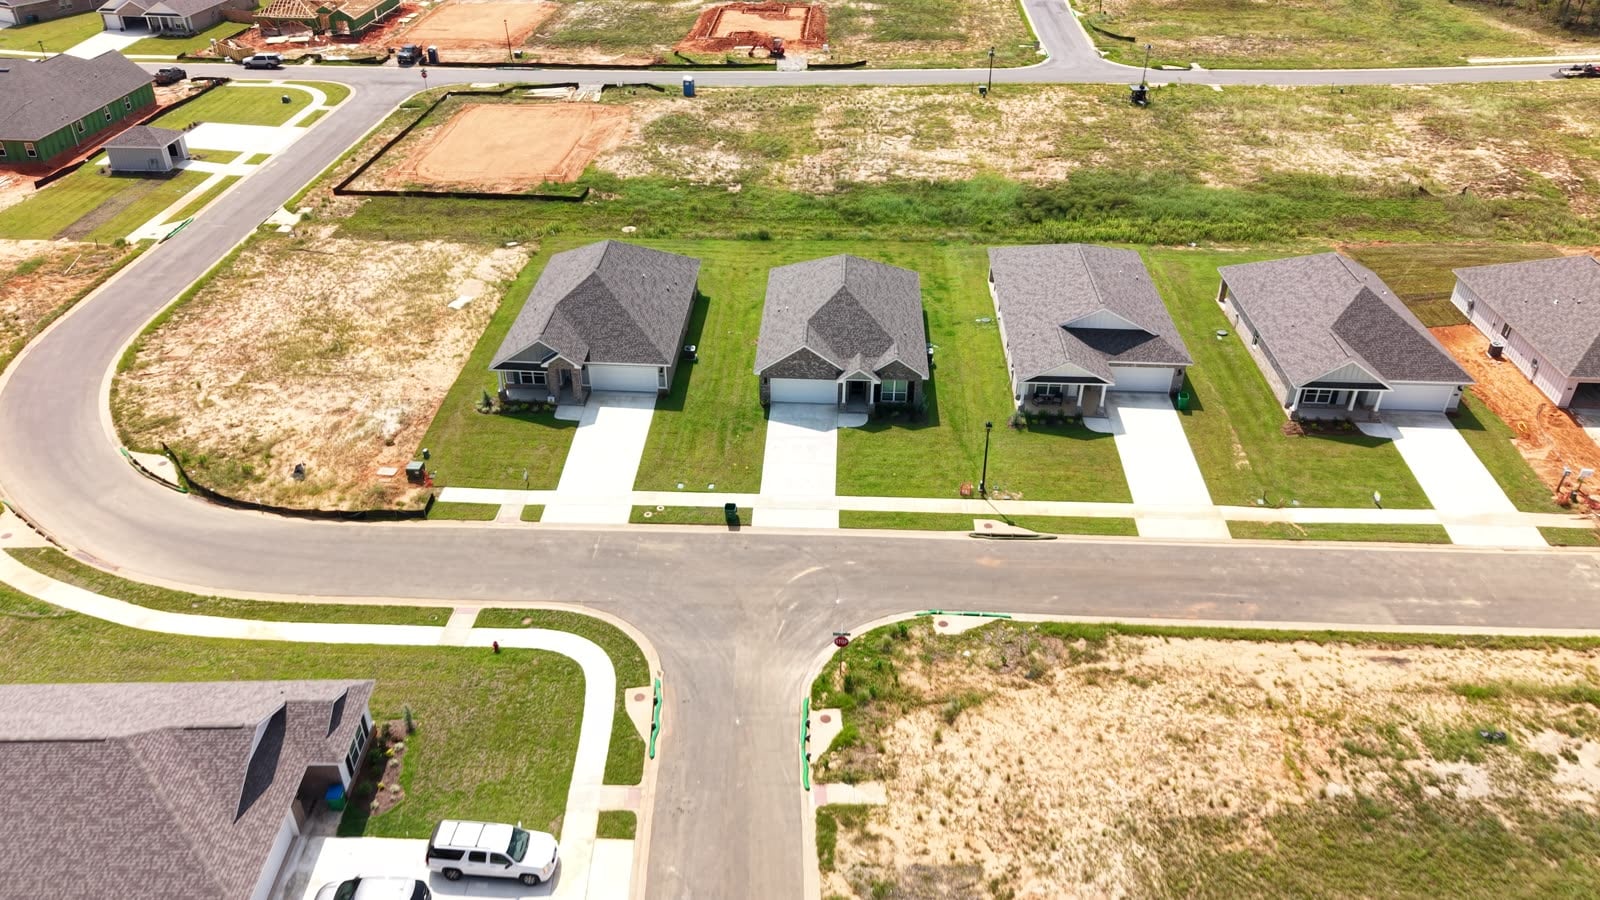
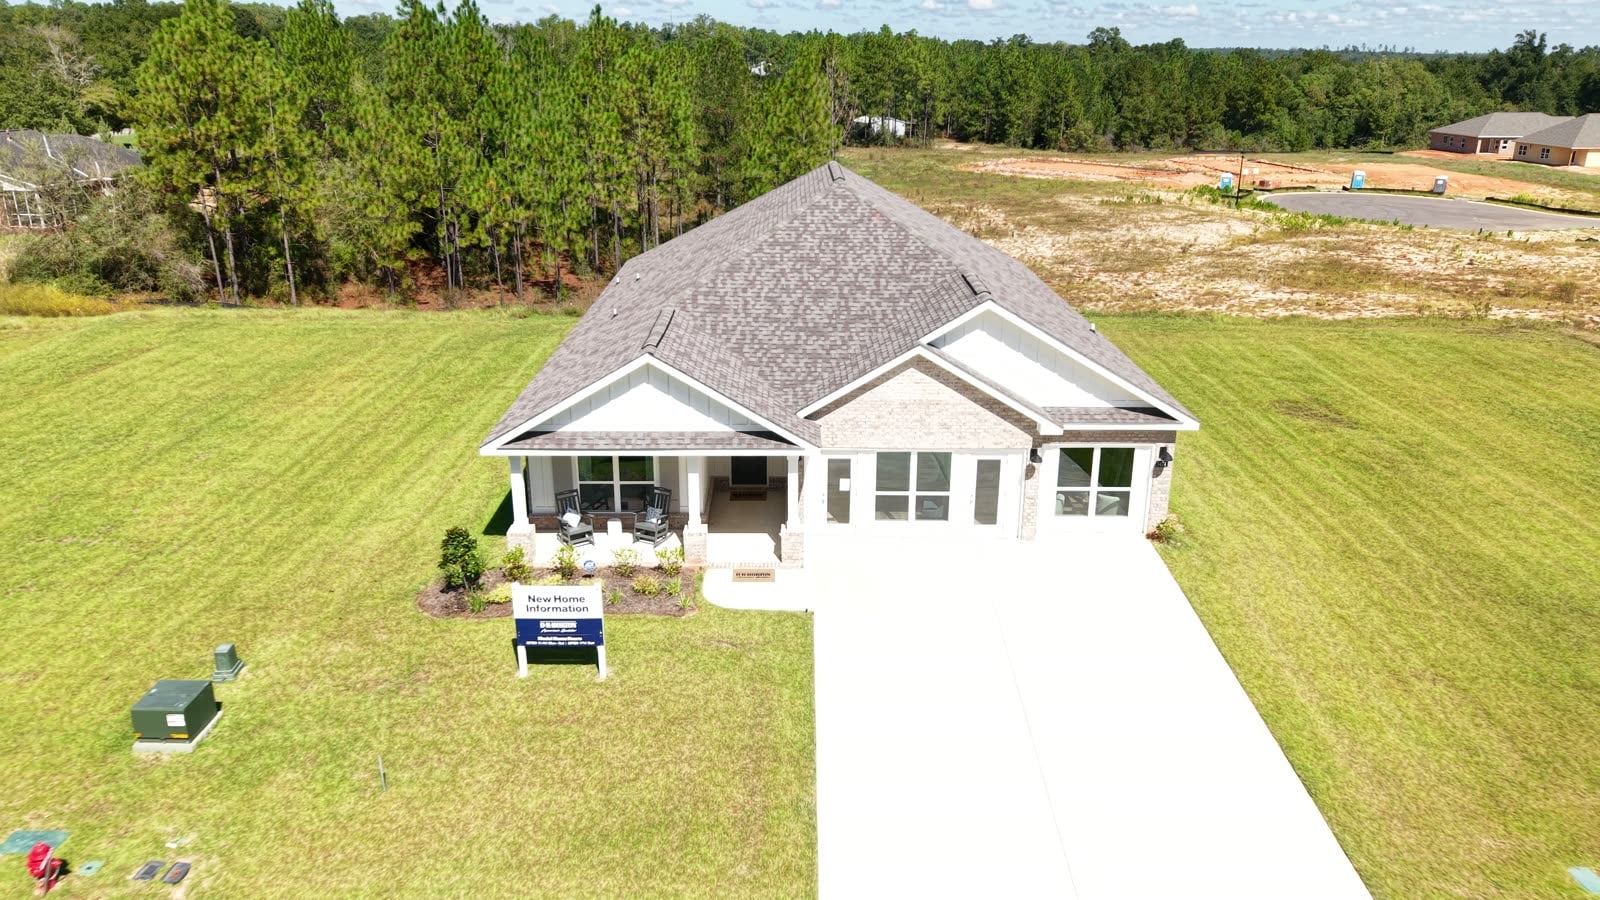
As I'm writing this, D.R. Horton advertises Bear Run homes from $329,900, with available homes going up from there depending on the floor plan, size, garage and lot. So if you're comparing a Bear Run home with an existing home elsewhere in Saraland, you can't just compare list price to list price. You have to compare the whole transaction.
The Builder's Lender Can Be a Real Advantage, If You Understand It
Because DHI Mortgage is D.R. Horton's affiliated lender, the builder can use incentives in ways an individual seller usually can't. A homeowner selling a resale home can offer concessions, but they aren't sitting next to a national mortgage company that can build financing programs around the homes it needs to sell.
That's one reason new construction can look more expensive on paper and still turn out surprisingly competitive on a monthly basis.
DHI Mortgage offers conventional, FHA and VA loans, among others, and in some situations, temporary buydowns. A temporary buydown lowers your payment for the first one, two or three years of the loan, and the seller or builder pays for it. You're still qualified at the full rate, and the rate steps up to the full rate when the buydown ends.
This matters because a builder may decide it would rather put money toward your financing than lower the price of the house. Depending on your situation, that can be a much better deal for you.
A $10,000 Lower Price Doesn't Automatically Mean the Cheaper House
Say you're deciding between a resale home in Saraland for $340,000 and a Bear Run home for $350,000. At first glance, the resale is cheaper.
Now say D.R. Horton is offering a financing incentive on the Bear Run home that meaningfully lowers your interest rate. Suddenly, that $10,000 price difference may not be the most important number anymore. A lower rate affects your payment every month you have the loan.
That doesn't mean the builder deal automatically wins. You still have to compare lender fees, points, closing costs, mortgage insurance if it applies, and how long you realistically expect to keep the loan. But a $340,000 home at one rate and a $350,000 home at a much lower rate are not the same financial decision. The price is only one variable.
This Is Where the Loan Estimate Matters
If I'm helping you compare DHI Mortgage with an outside lender, I want both Loan Estimates in front of us. Not a text message saying "my lender can beat that," not an advertised rate, and not a screenshot of a social media ad. The actual Loan Estimate.
That document lets us compare the interest rate and APR, lender charges, mortgage insurance, prepaid items, estimated cash to close and the projected monthly payment. I also want to know whether the rate is permanent or temporary, and whether the offer changes depending on which house you choose.
What we compare on both Loan Estimates
- Interest rate and APR
- Lender charges
- Mortgage insurance
- Prepaid items
- Estimated cash to close
- Projected monthly payment
- Whether the rate is permanent or temporary
- Whether the offer changes by house
As of this writing, DHI Mortgage's affiliated business disclosure for Mobile County lists a loan origination charge and a processing fee, with an additional charge possible on certain affordable housing loan programs. The same disclosure names affiliated title and insurance companies, DHI Title of Alabama and D.R. Horton Insurance Agency.
None of that is good or bad on its own. It's part of the transaction, and I want to see all of it. A low rate with expensive fees can be less attractive than it first looks. A slightly higher rate with lower costs can sometimes make more sense, especially if you don't expect to keep the loan for decades. The only way to know is to compare the full offer.
The Builder Incentive Isn't Free Money
This is one of the most important things to understand. DHI Mortgage explains that temporary buydowns are paid for by the seller or builder, and that builder money used for a buydown may limit how much is left for your other closing costs.
There's no free money.
There are only different ways to use the builder's money, and you may have a real decision to make about where it goes. You might need help with cash to close. You might benefit more from a permanent rate reduction. A temporary buydown might help you ease into the payment. These options aren't interchangeable.
If you have plenty of cash and your focus is keeping the monthly payment down, the answer may be one thing. If your biggest concern is keeping cash in the bank after closing, it may be something completely different. A buyer using a VA loan may have a different set of priorities altogether.
So I don't think buyers should simply ask, "What incentive is D.R. Horton offering?" The better question is, "Which incentive is most valuable for me?" The best one isn't always the biggest number. It's the one that solves the most expensive problem in your transaction.
Pay Attention to Insurance
This is the other place the economics can shift. D.R. Horton says Bear Run homes receive a FORTIFIED Gold certificate. That matters, because insurance in South Alabama is a significant cost, and FORTIFIED Gold homes may qualify for meaningful discounts on the wind portion of the premium, depending on the carrier and the property.
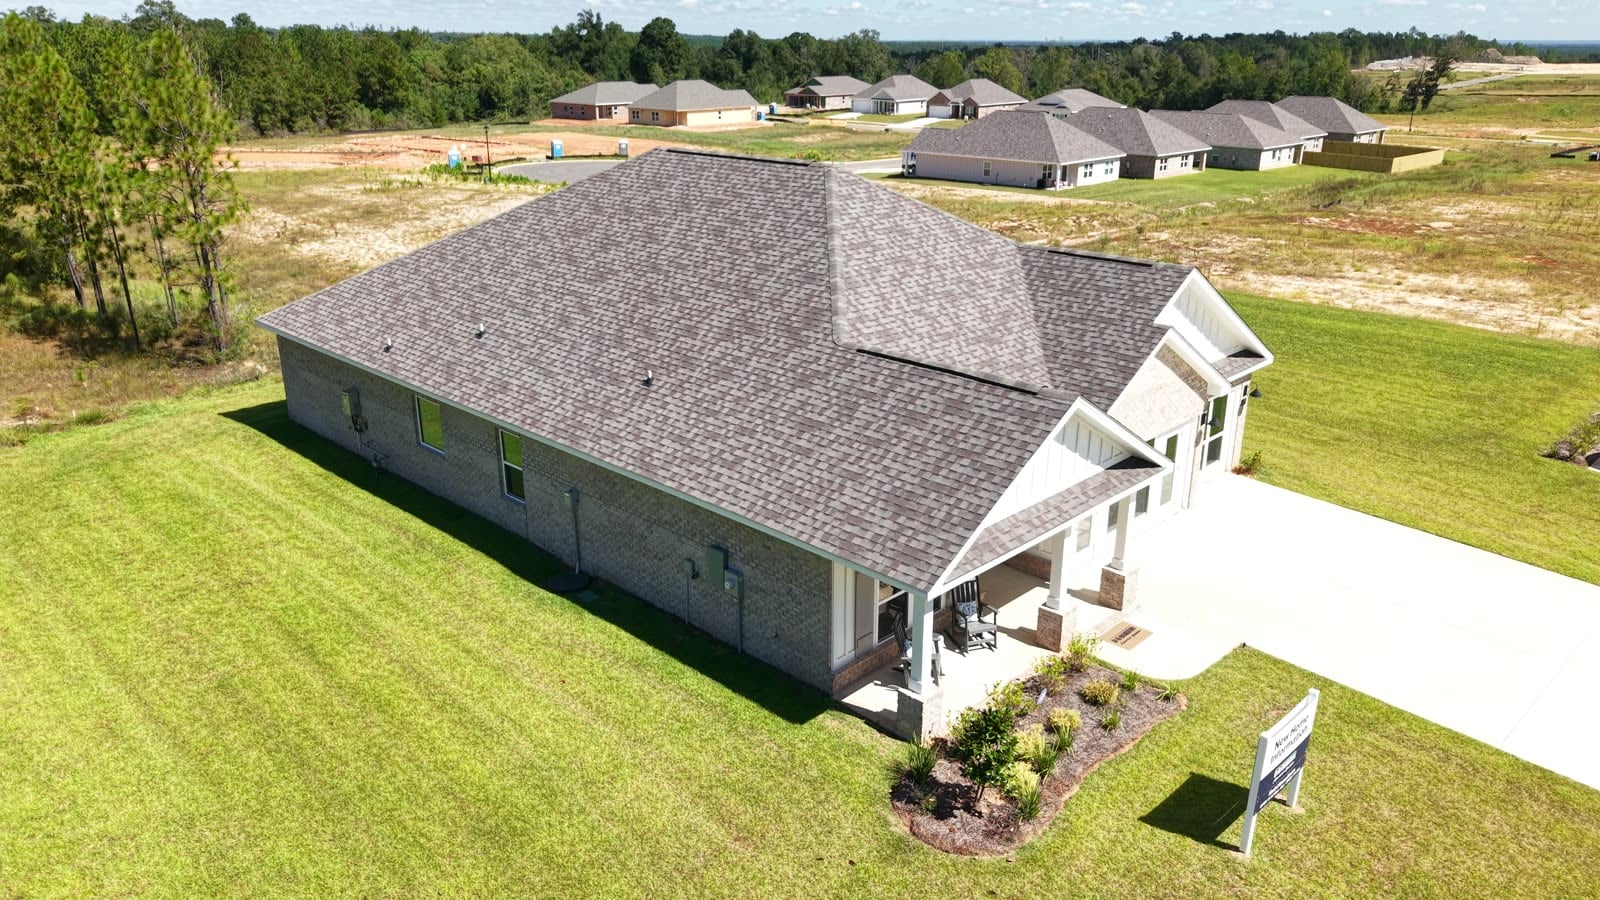
That doesn't mean a Bear Run home will automatically have cheap insurance. It means I want a real quote on the Bear Run home and a real quote on the resale home we're comparing it with. If the Bear Run home costs a little more but the insurance is meaningfully lower, that matters. If the difference is small, that matters too. I don't want to guess. I want the actual number.
Then There's Everything You'll Spend After Closing
This is where new construction can fool people a little. A brand-new home can still need a surprising amount of money before it feels finished. You may want a fence, window treatments, gutters, garage storage, more landscaping or a screened porch.
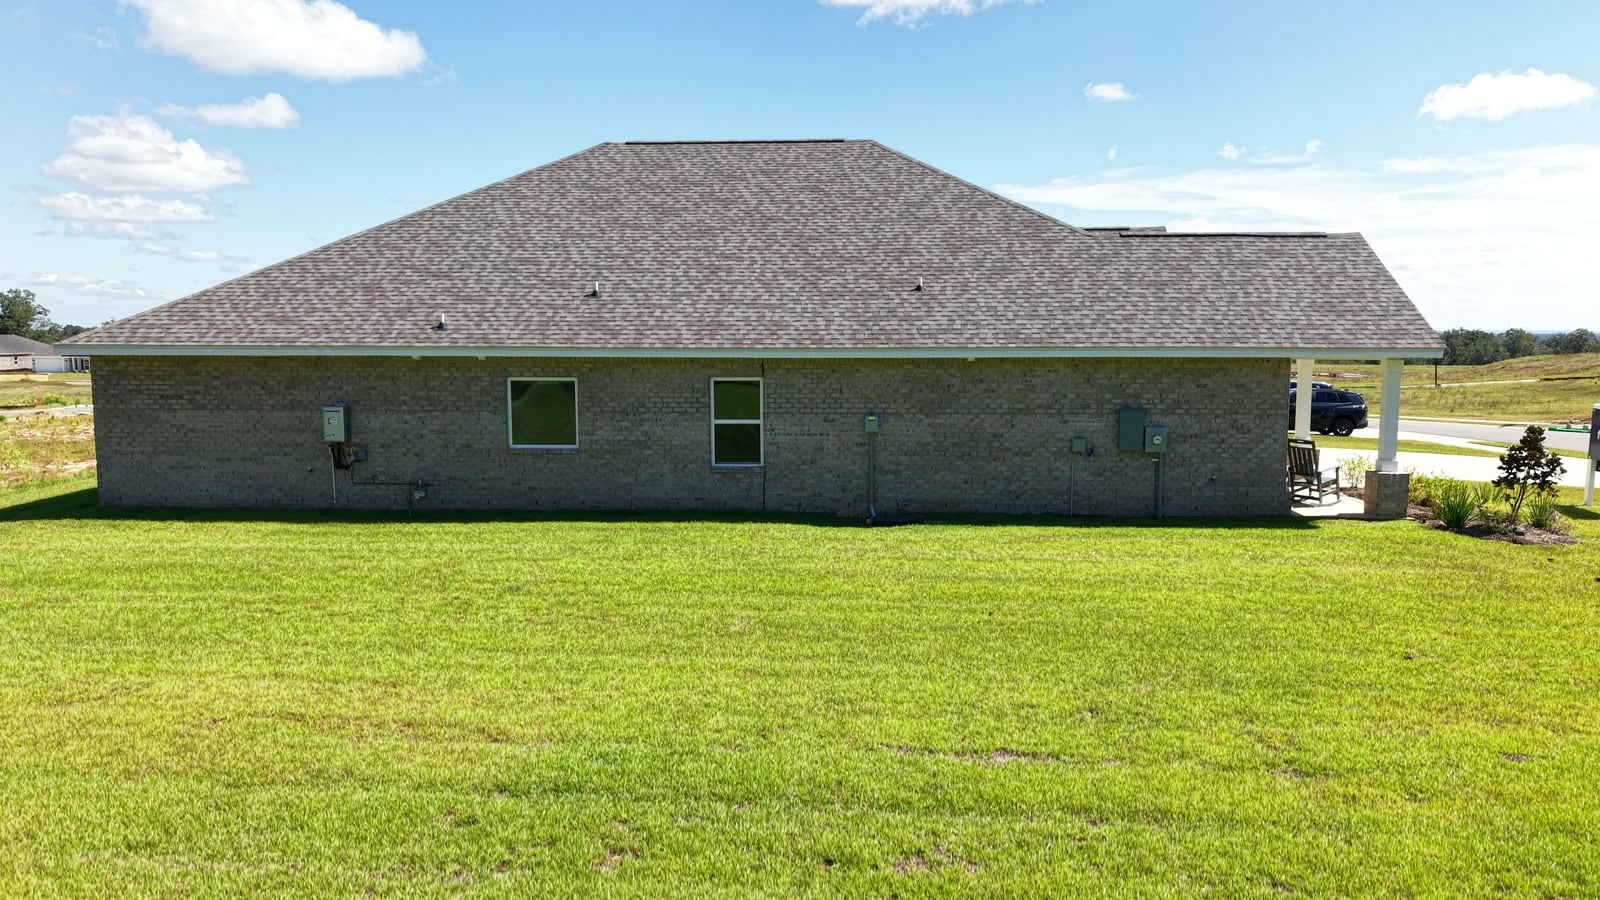
None of those are reasons not to buy new. They just need to be in the budget. The resale home down the street may already have a fence, mature landscaping, a storage building, blinds and a screened porch. Of course, that same home may also have an older air conditioning system, an aging roof and appliances near the end of their life.
That's why comparing new construction with resale isn't as simple as asking which house costs less. You have to look at what you're actually buying and what you're likely to spend once you own it.
The Builder Has More Tools Than a Resale Seller
This is really the point. D.R. Horton can adjust the price. It can offer help with closing costs. It can work through DHI Mortgage to offer financing incentives on certain homes, and it can sometimes put money toward a temporary or permanent buydown.
That doesn't make Bear Run automatically the better deal. It means you should take the financing seriously. If you compare a Bear Run home with an existing home in Saraland and ignore the builder financing, you aren't really comparing the two purchases. You're comparing the price tags.
I'd Still Shop the Loan
Even when DHI Mortgage is offering a strong incentive, I'd still want to know what another good lender can do. Not because I assume the outside lender will win. Sometimes it won't. If D.R. Horton is heavily subsidizing the financing on a particular home, that offer may be very hard for an outside lender to beat, and that's perfectly fine.
You generally don't have to use the builder's lender to buy the home, but you may have to use it to get a specific incentive. Ask the builder to put the incentive's requirements in writing.
If DHI has the better deal after we compare the whole package, use DHI. The goal isn't to prove one lender is better than another. It's to know why you're choosing the one you choose.
If You're Flexible, You Have Leverage
This is where new construction shopping gets interesting. D.R. Horton may be more motivated to sell one finished home than another. Maybe it's been sitting longer. Maybe they're closing out a phase. Maybe a specific house is tied to a financing promotion. Or maybe several floor plans would work for you, and one simply comes with a much better incentive package.
If you tell me you'll only consider one exact house, we may not have much room to work. If you tell me you like three floor plans and would be happy with several available homes, now we can compare the deals. That's when I want to know which house the builder is most motivated to sell.
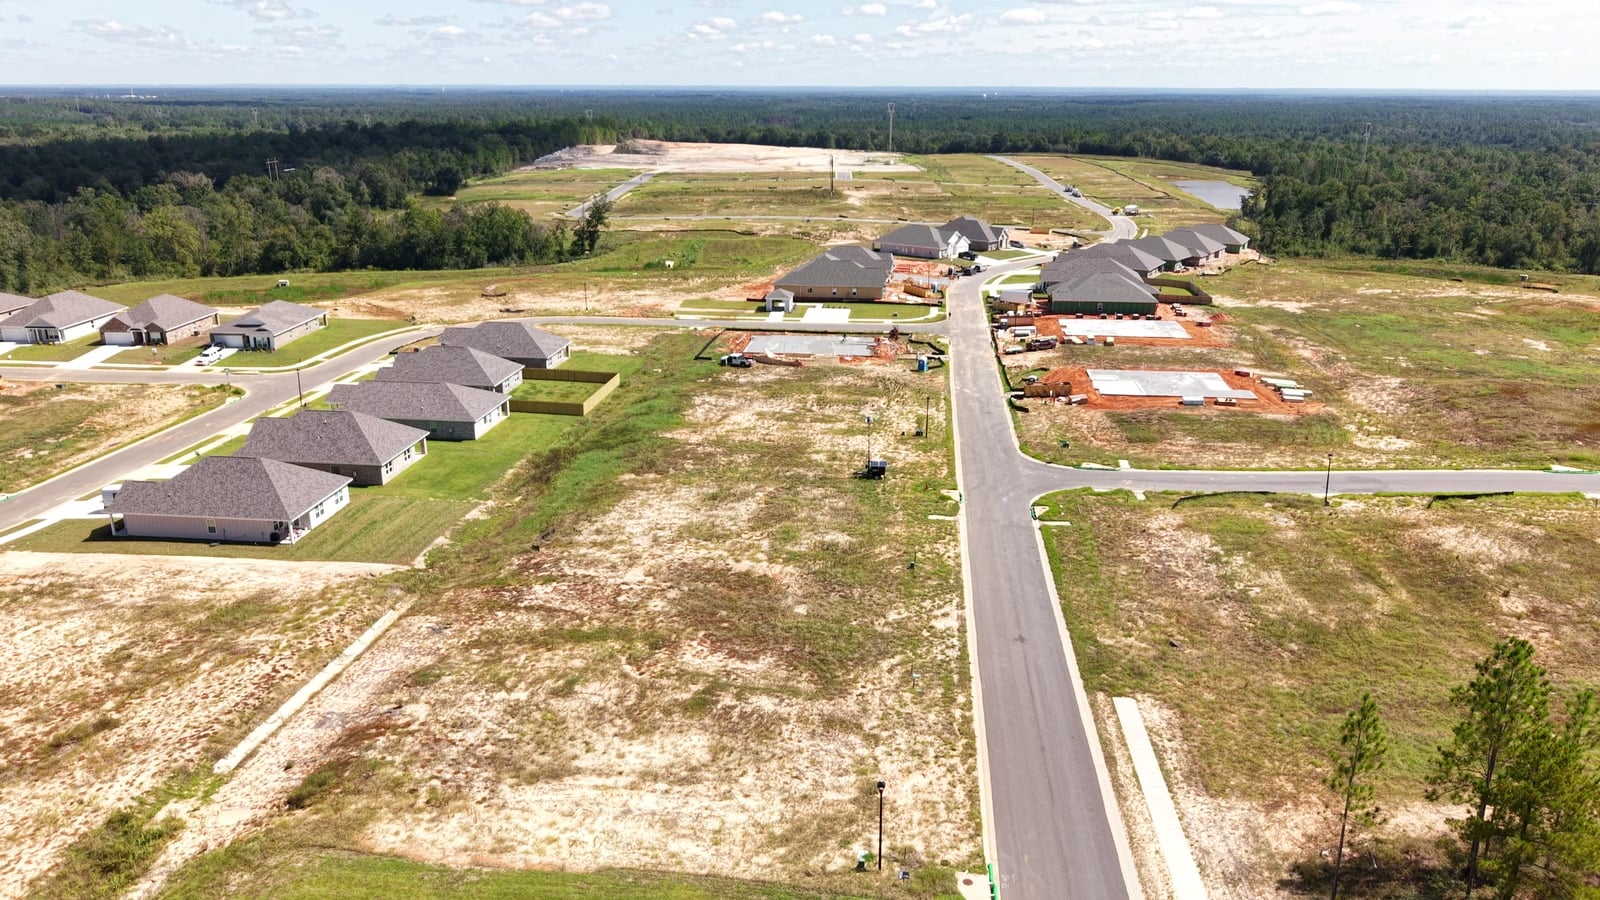
The best value in Bear Run may not be the least expensive house. It may be the one with the best combination of price, lot, financing and incentives.
So How Much Does It Really Cost?
There isn't one answer. The real cost is the purchase price, interest rate, lender fees, closing costs, insurance, cash needed at closing and what you're likely to spend after you move in, all together. That's the number I care about.
When you compare Bear Run with an existing home in Saraland, the real difference can be much smaller or much larger than the list prices suggest. The only way to know is to put the actual numbers side by side.
That's how me and my team approach it. We look at the current D.R. Horton inventory, find out which homes carry financing incentives, compare DHI Mortgage with an outside lender, get insurance quotes, figure out the cash you'll need to close, and then put the best Bear Run option next to the resale homes in the same budget.
Let's compare the whole deal.
At that point, we aren't guessing which house is the better deal. We're actually comparing them, and that's a much better way to buy a home.
Compare Bear Run With Our TeamCheck out this article next